The Building Cost Information Service (BCIS) is the leading provider of cost and carbon data to the UK built environment. Over 4,000 subscribing consultants, clients and contractors use BCIS products to control costs, manage budgets, mitigate risk and improve project performance. If you would like to speak with the team call us +44 0330 341 1000, email contactbcis@bcis.co.uk or fill in our demonstration form
Published: 19/10/2026
EY-Parthenon publishes its profit warnings report on a quarterly basis(1). The report outlines the profit warnings issued by FTSE companies across different sectors and provides analysis on the driving factors behind them.
Profit warnings are statements issued to the stock exchange by listed companies to declare that their full-year profits will be materially below management or market expectations.
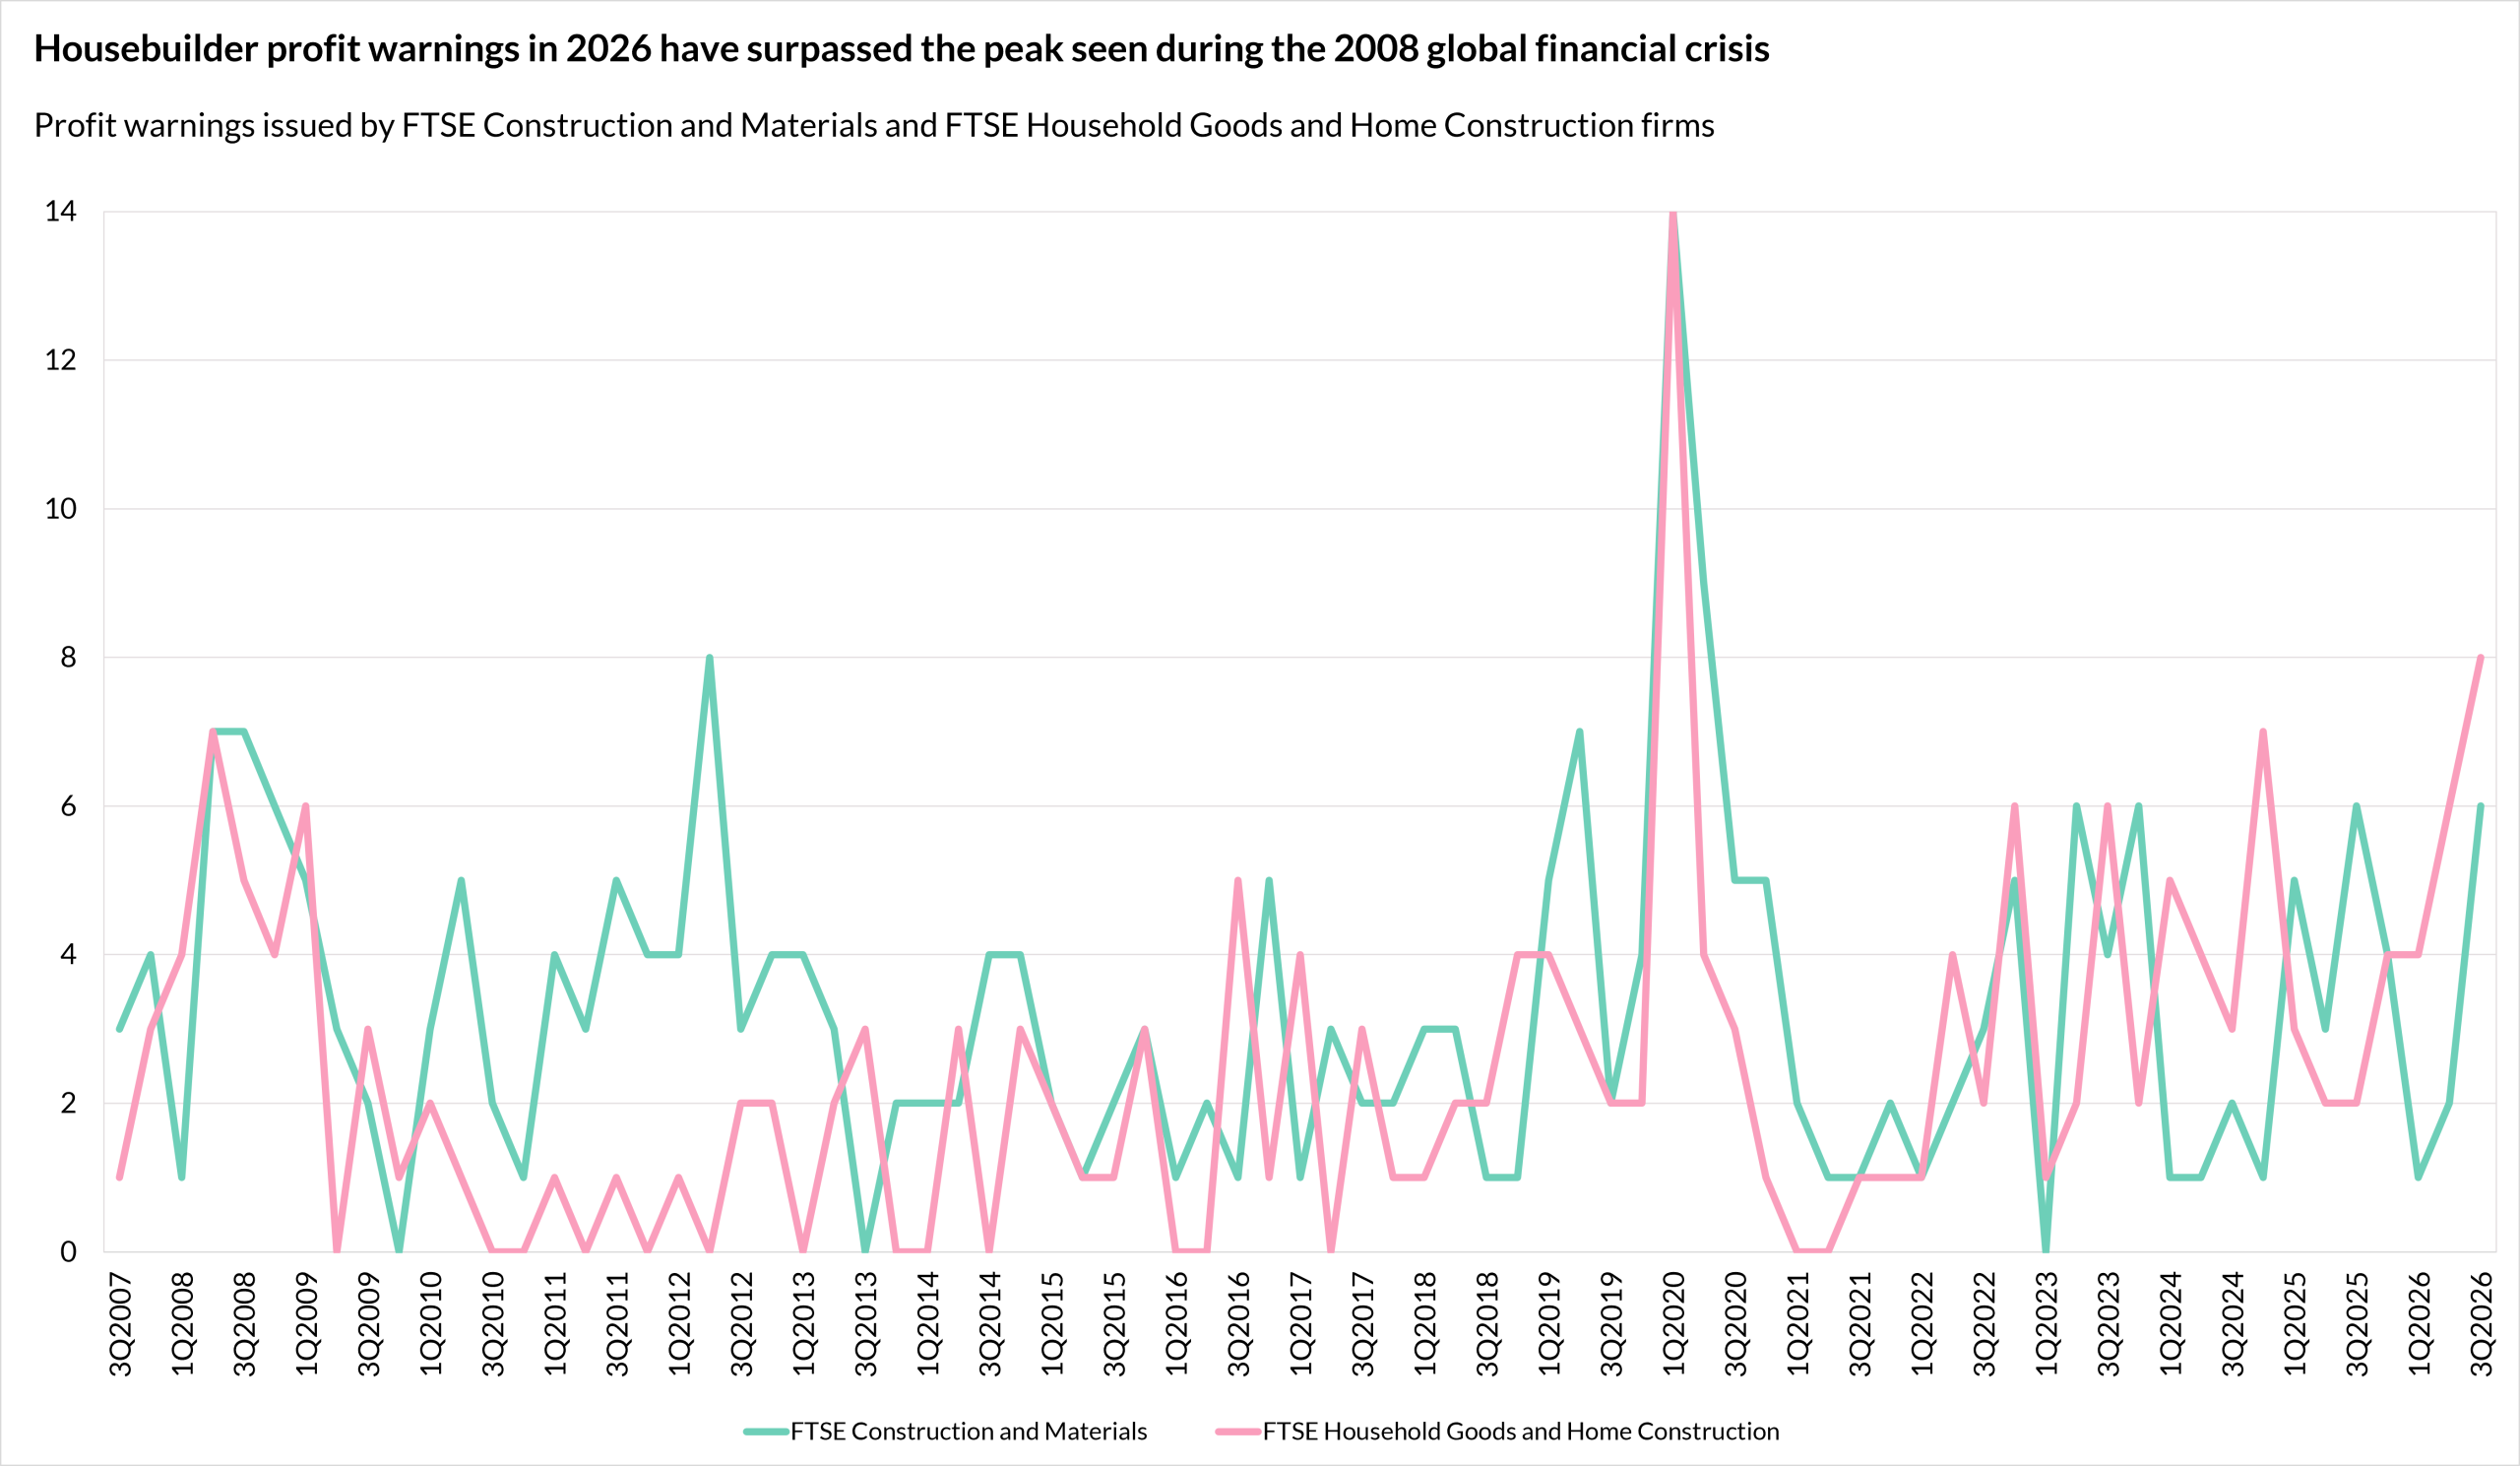
Housebuilder profit warnings surpass peak in 2008 global financial crisis
Housebuilders have issued more profit warnings in 2026 than at the peak of the 2008 global financial crisis, according to new data from EY-Parthenon.
FTSE Household Goods and Home Construction companies, which include housebuilders, issued a total of eight warnings in 3Q2026, six of which came from housebuilders.
This took the total warnings issued by housebuilders in 2026 so far to 14, higher than the 10 recorded during the financial crisis. The wider FTSE Household Goods and Home Construction sector has issued 16 warnings in 2026 to date.
Source: EY-Parthenon, Analysis of UK Profit Warnings
In the 12 months to the end of the third quarter, the FTSE Household Goods and Home Construction sector reported the second highest percentage of companies warning of any FTSE sector, at 58%.
Dr David Crosthwaite, chief economist at BCIS, said: ‘The latest profit warnings data provide further evidence of the mounting pressures on housebuilders and serve as a timely warning ahead of the Budget. There is no quick or straightforward route out of the current housing downturn. Sooner rather than later, the government must recognise that the cumulative burden of development costs is quickly unravelling viability and constraining the sector’s ability to deliver on housing targets or contribute to economic growth.
‘Addressing these pressures will require more than incremental policy adjustments. The government could for example reconsider regulatory costs imposed on development, including the funding mechanism for the Building Safety Levy, alongside measures to reduce inflationary pressures feeding through from volatility-exposed supply chains. Continued investment in planning capacity and measures to stimulate housing market demand will also be essential.
‘These are not easy decisions. Some may require a reassessment of the pace or implementation of environmental and building safety requirements. But there is a fundamental distinction between weakening policy ambitions and ensuring the industry has the financial capacity to deliver them.
‘The real question ahead of the Budget is whether the government is prepared to address the structural pressures holding back housing delivery, or whether it will continue to rely on marginal interventions and hope that an improvement in economic conditions can do the heavy lifting.’
EY-Parthenon’s report provides further insight into the structural pressures facing housebuilders. Despite the introduction of the Your First Home scheme, further interest rate increases are expected to prolong affordability challenges, with elevated mortgage rates continuing to weigh on buyer demand.
The report also highlights the growing burden of long-term liabilities, including regulatory and remediation costs, which are adding to existing development cost pressures. Combined with slower sales rates and increased investor scrutiny, these factors could make it more difficult for developers to access finance on favourable terms.
Against this backdrop, EY-Parthenon anticipates an increase in restructuring activity among housebuilders and across the wider supply chain, as persistent structural pressures continue to strain liquidity, balance sheets and business models.
Construction and materials firms are also feeling the heat
Elsewhere, FTSE Construction and Materials firms remain under pressure, issuing six profit warnings in 3Q2026, up from two in the previous quarter. This represented the third-highest quarterly total across all FTSE sectors.
The increase in warnings reflects the impact of continued uncertainty on investment decisions, with projects and transactions delayed and fewer opportunities converting into confirmed work. EY-Parthenon highlighted the sector’s sensitivity to business confidence and project timing, with prolonged uncertainty continuing to weigh on activity.
The report also illustrates how pressures affecting construction and related markets are feeding through to the wider economy. FTSE Industrial Support Services firms, in particular, remain exposed to subdued activity across the construction, infrastructure and industrial sectors. According to EY-Parthenon, weaker customer confidence, repeated delays to the anticipated recovery and persistently high interest rates have constrained activity in these markets, undermining demand and reducing revenue visibility.
UK profit warnings neared two-year high as geopolitical conflict bites
A total of 65 profit warnings were issued by UK-listed companies across all FTSE sectors in the third quarter of 2026. This was the highest quarterly total since 4Q2024, almost two years earlier, bringing the year-to-date total to 179.
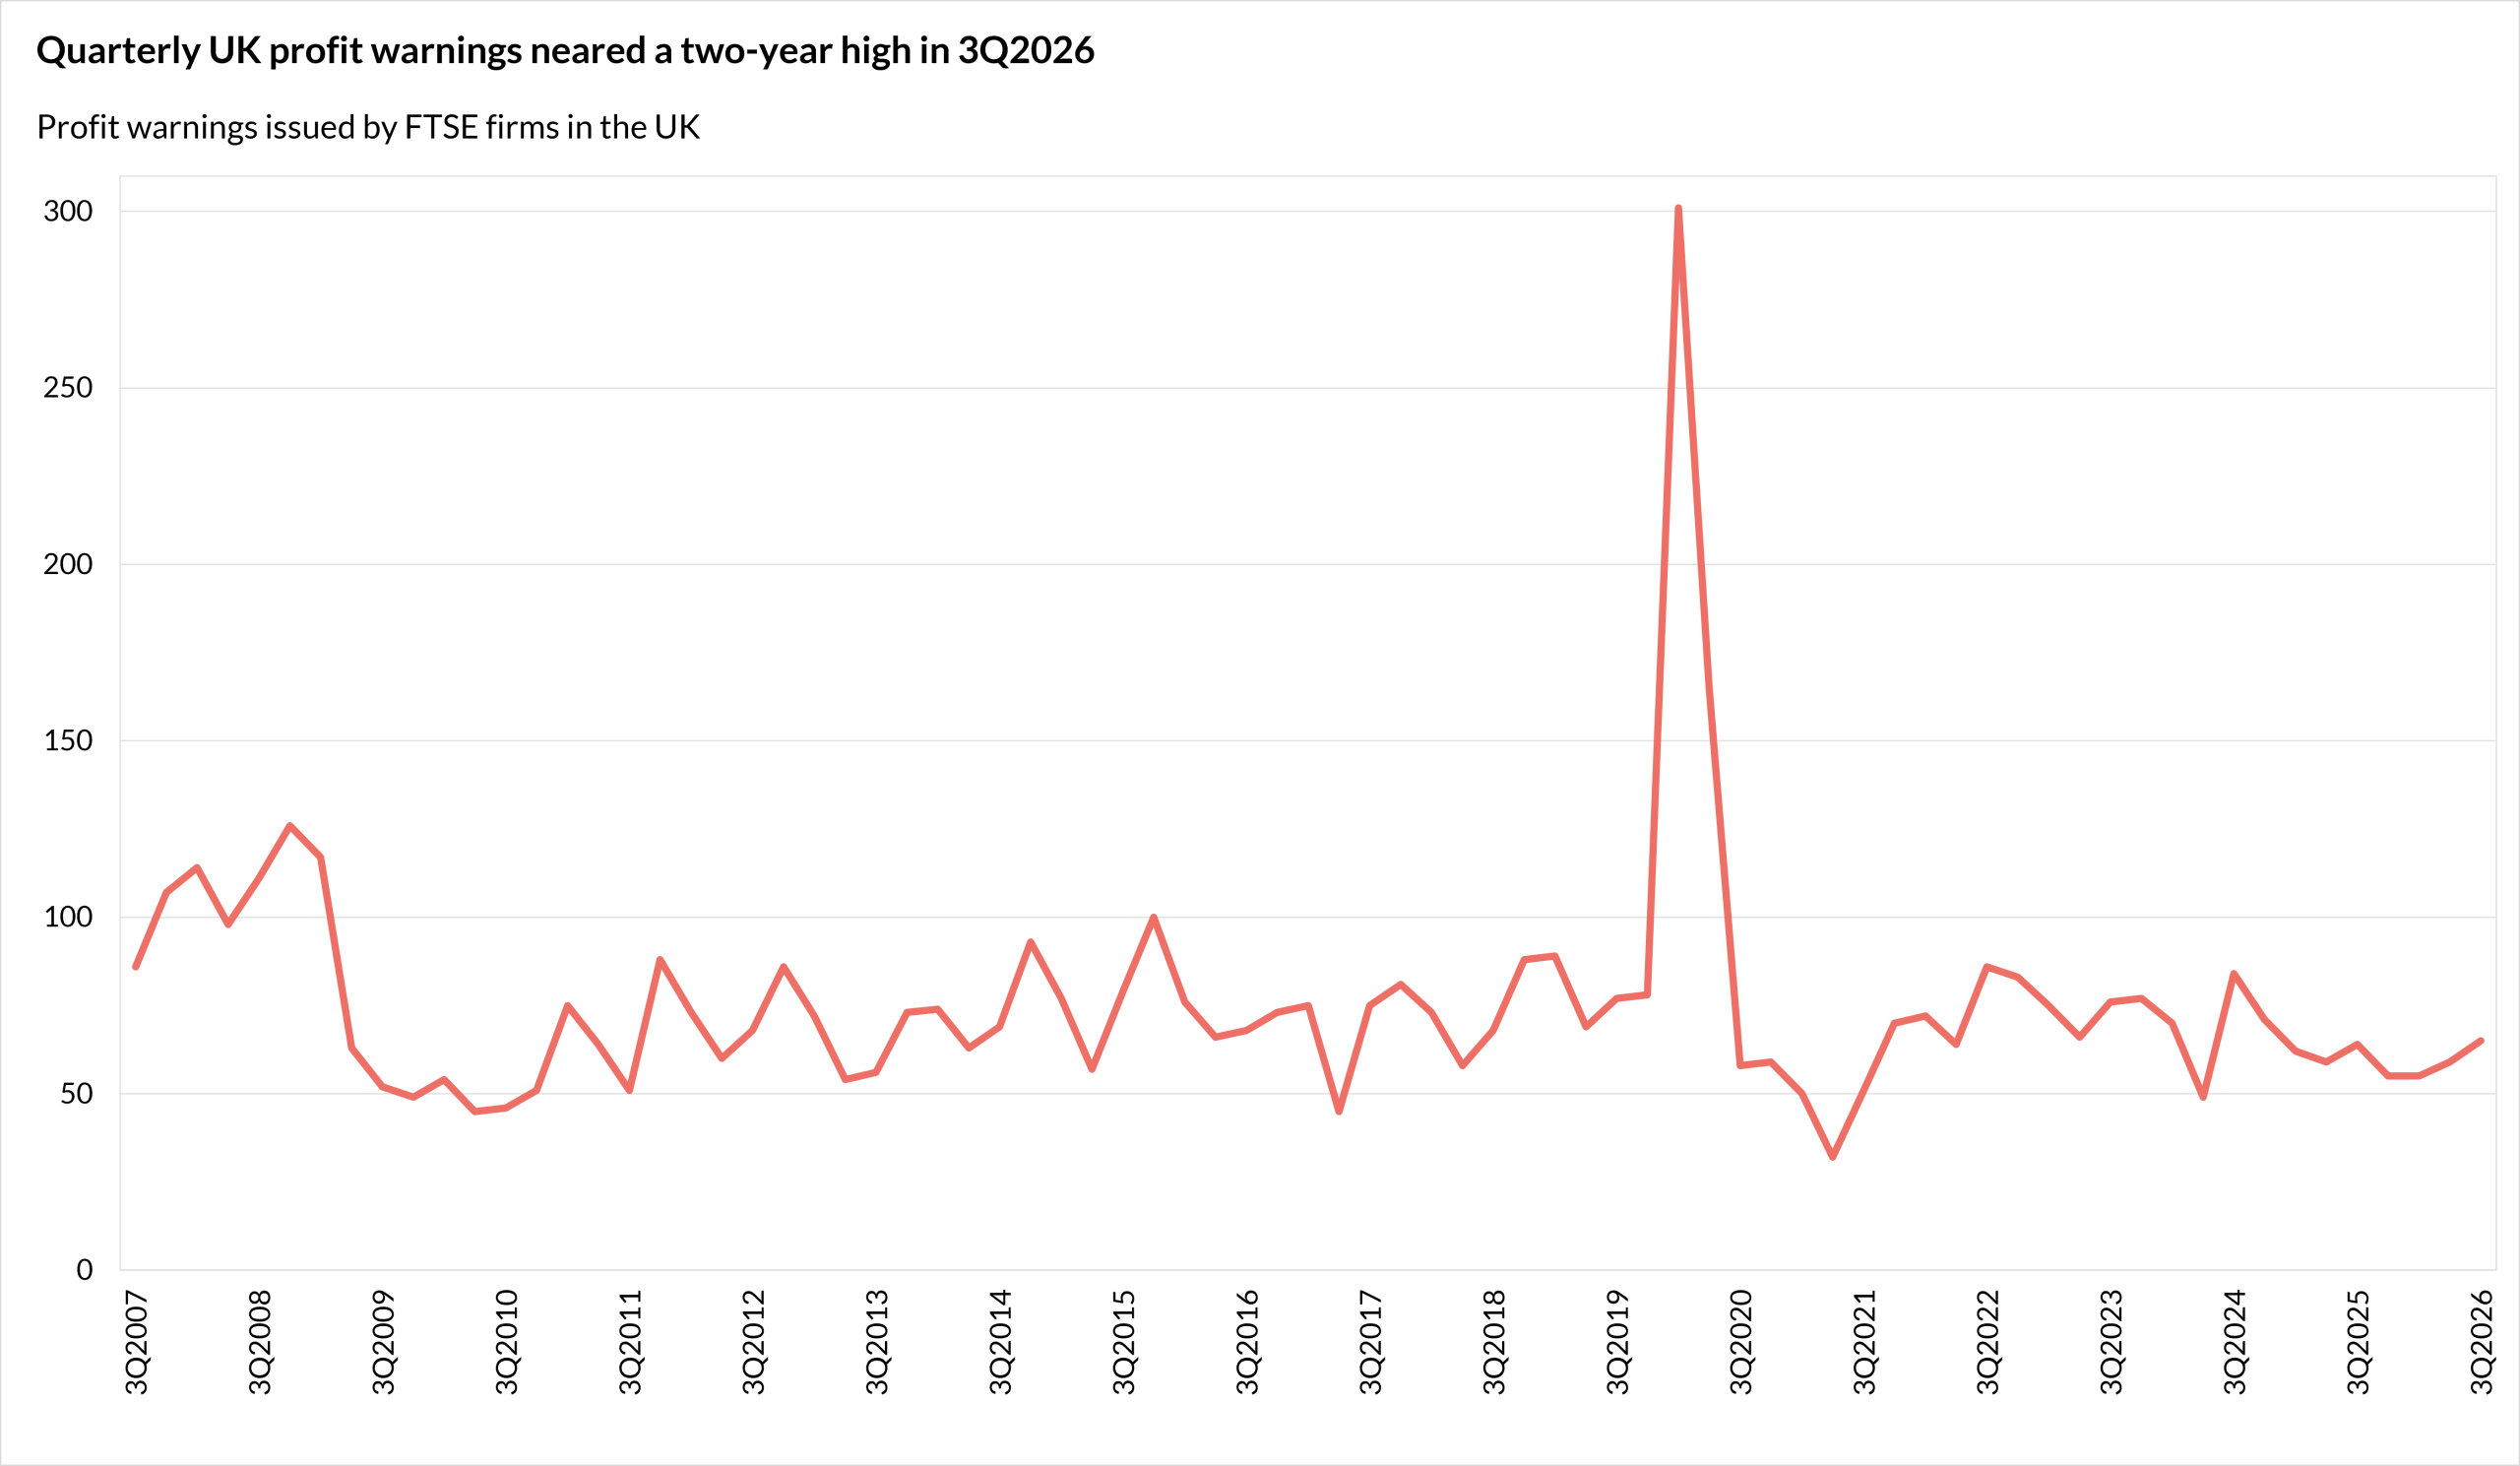
Source: EY-Parthenon, Analysis of UK Profit Warnings
More than half (54%) of warnings issued in 3Q2026 were attributed to geopolitical and policy changes and uncertainty, while 38% specifically cited the impact of the Middle East conflict. Cost-related warnings also reached their highest level since 2022.
In its analysis, EY-Parthenon suggested that the latest figures reinforce a broader shift in economic conditions since the pandemic. Supply-side disruptions have become more frequent and interconnected, with pressures such as materials shortages, trade tariffs and geopolitical instability combining to drive up business costs. These pressures can also contribute to inflationary persistence, complicating the outlook for interest rates and financial markets.
The report warned of a challenging earnings environment ahead, as economic uncertainty, geopolitical disruption, technological change and elevated financing costs continue to overlap. While highlighting the resilience businesses have demonstrated in navigating previous challenges, EY-Parthenon cautioned that some of the external conditions that supported them in the past may prove less reliable in the years ahead.
The government’s fiscal position has also become more constrained, limiting its capacity to cushion the economy against further shocks.
‘The wider economy urgently needs a boost from the Budget, but the Chancellor faces a difficult balancing act,’ Dr Crosthwaite added. ‘Any measures to stimulate growth must be weighed against the risk of unsettling bond markets and pushing up government borrowing costs.
‘For construction, a stronger wider economy would ultimately translate into increased demand and activity. Equally, a more buoyant construction sector would, through its multiplier effect, help stimulate growth across the wider economy.
‘Supporting businesses at the Budget could offer one of the clearest routes to strengthening demand, encouraging investment and supporting a sustained economic recovery. While recent improvements in headline growth figures are welcome, they do not necessarily capture the challenges still facing businesses and the wider economy. The priority should be to build on these signs of improvement while creating the conditions for more sustained investment and demand.’
To keep up to date with the latest industry news and insights from BCIS, register for our newsletter here.
(1) EY-Parthenon – Analysis of UK profit warnings – here