BCIS CapX provides a comprehensive, detailed and easy-to-use method of measuring cost movement for building and civil engineering. Widely used in the construction and infrastructure sector to help fairly allocate risk between the client and sub-contractors.
Published: 08/10/2026
Each month the Department for Business and Trade (DBT) publishes construction materials price indices (CMPIs), categorised under All Work, New Housing, Other New Work and Repair and Maintenance, as well as tracking a selection of building materials and components for the UK(1). BCIS data is used in the compilation of the DBT indices(2).
The Builders Merchant Building Index (BMBI) report(3) analyses market trends using data from the Builders Merchant Panel produced by GfK (Growth from Knowledge), a subsidiary of NielsenIQ (NiQ).
Steel and pipe prices still among leading sources of inflationary pressure
Construction materials prices for All Work rose by 6.4% in the 12 months to August 2026, according to the latest provisional data published by DBT. This was the highest level of annual growth in the All Work index since the 8.5% year-on-year increase recorded in March 2023.
New Housing recorded a 5.6% increase while Other New Work rose by 7.4% and Repair and Maintenance increased by 5.9% when comparing August 2026 with August 2025.
DBT’s CMPIs are compiled using a combination of resource cost indices produced and published by BCIS. These are based on BCIS Price Adjustment Formulae Indices (PAFI).
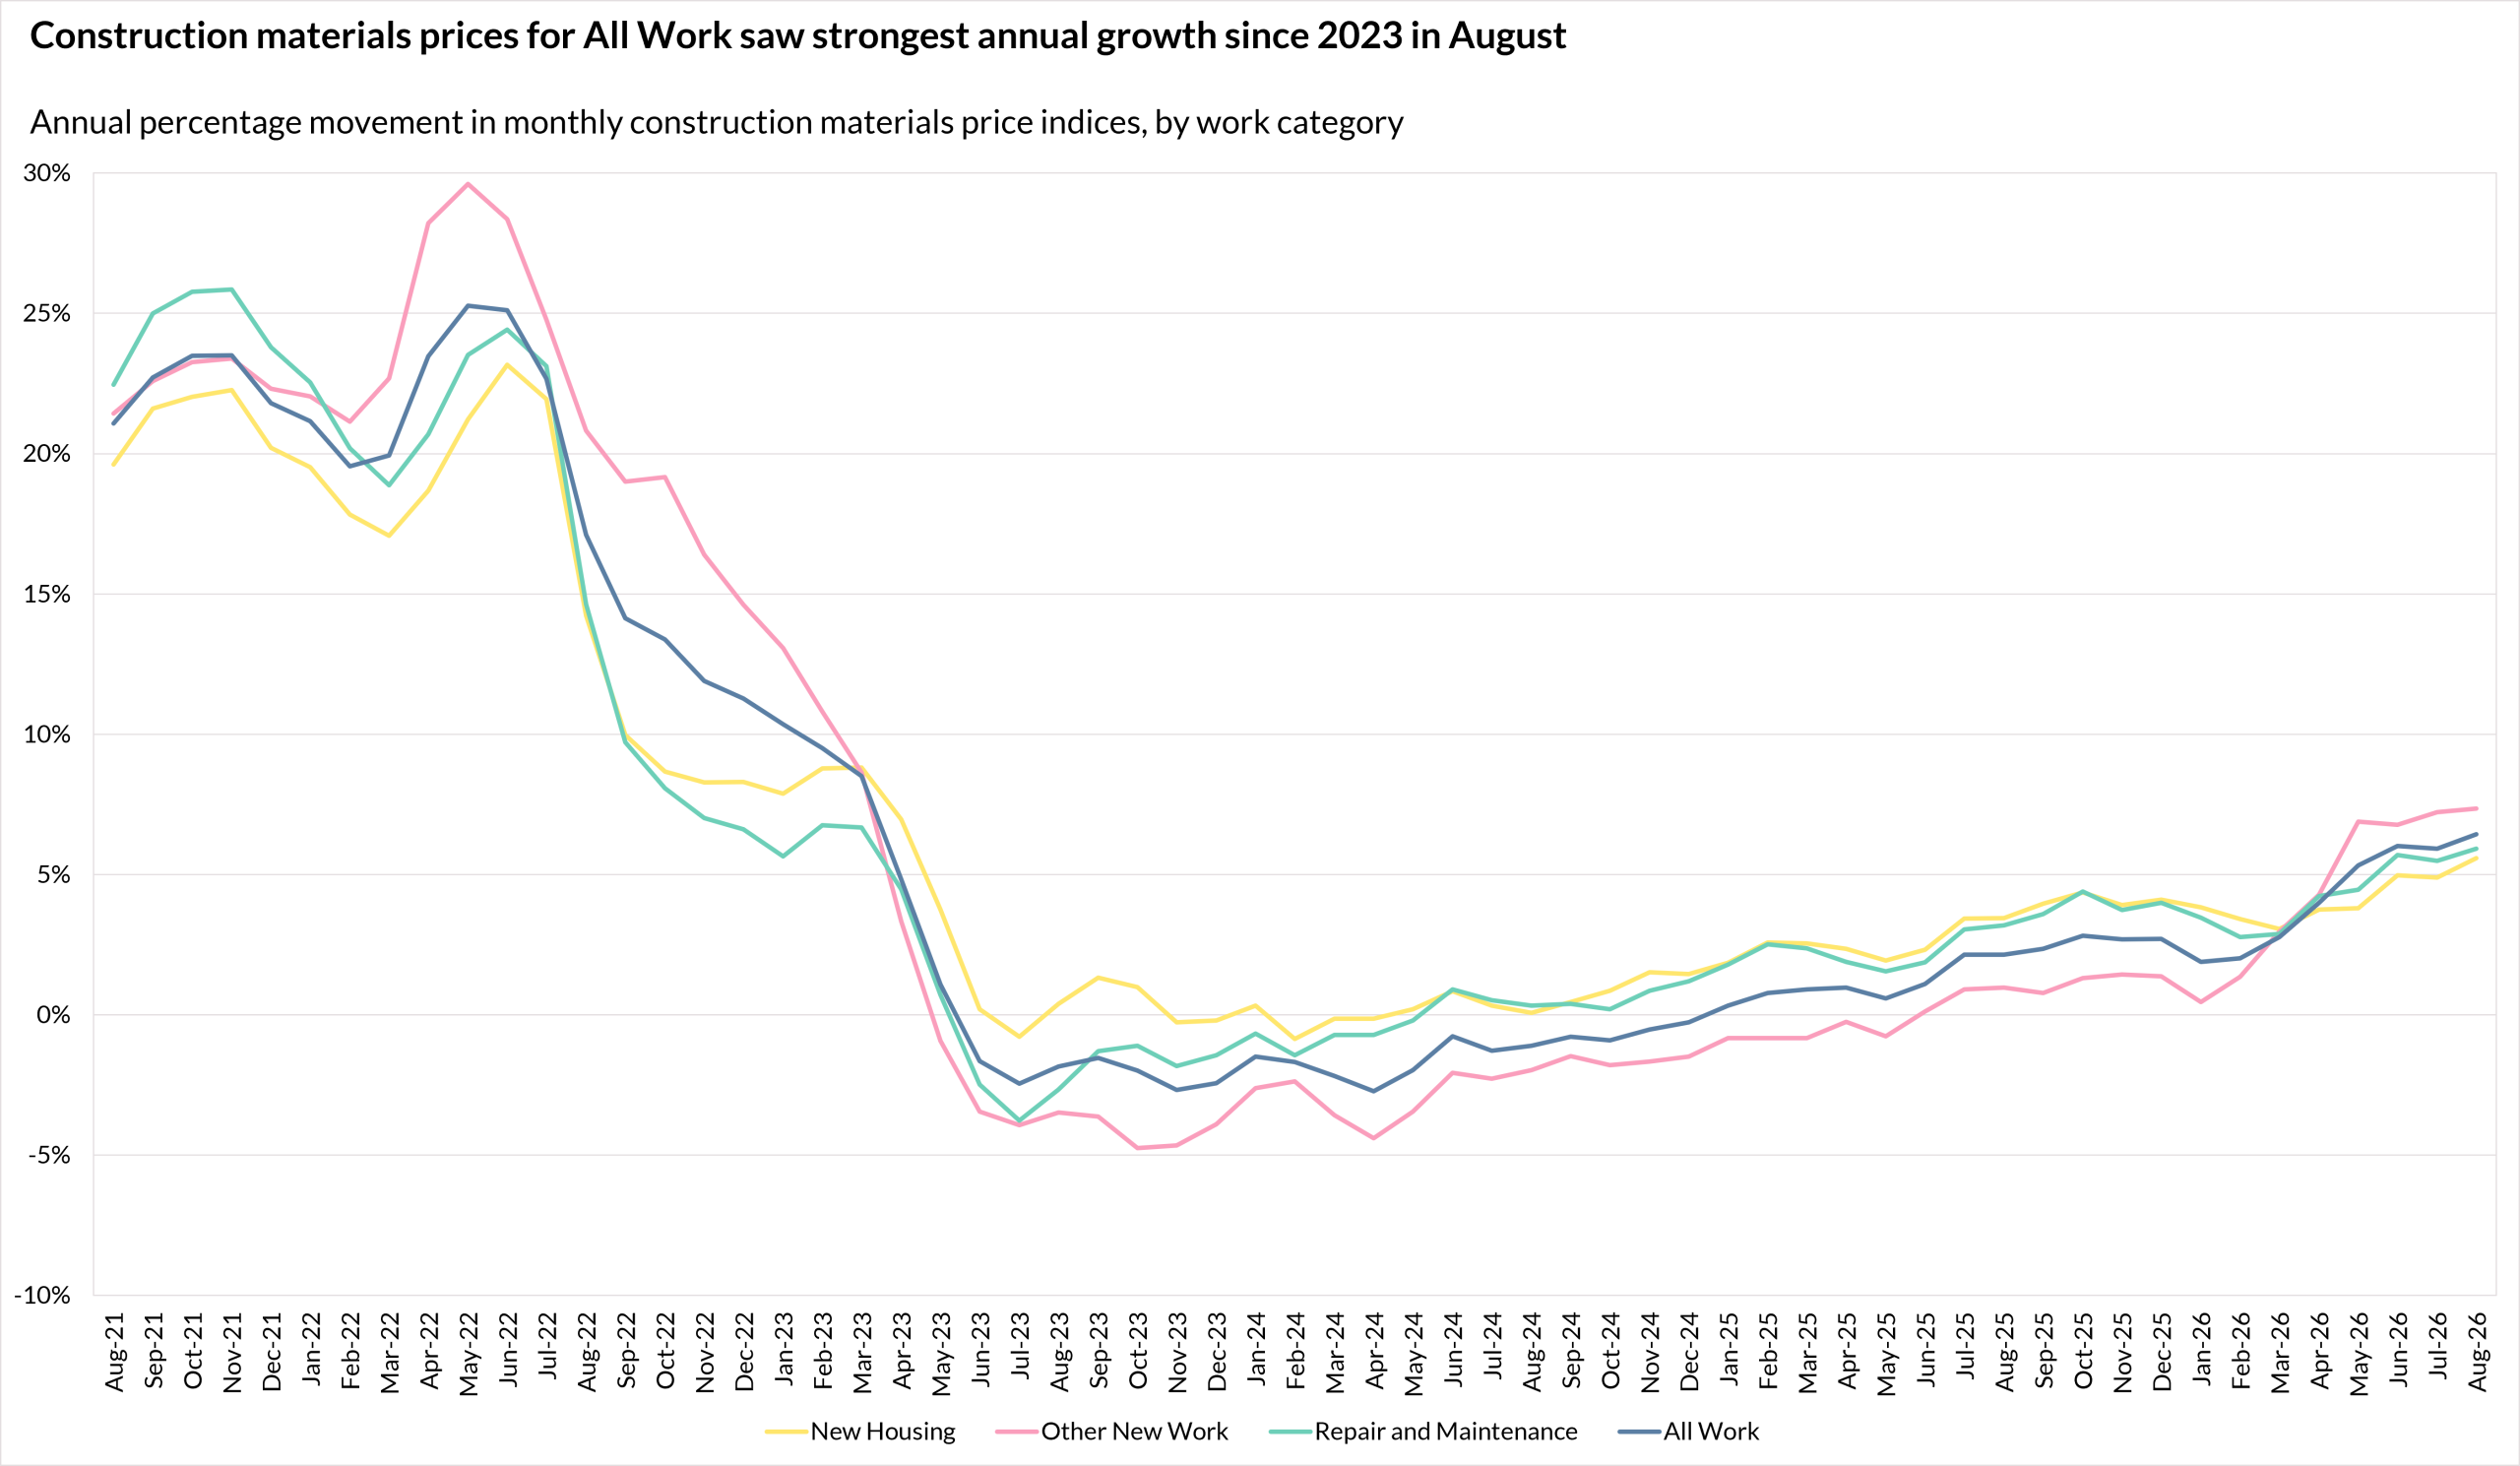
Source: Department for Business and Trade – Building materials and components statistics, Table 1a
Sam Parkin, senior economist at BCIS, said: ‘We’re continuing to see cost pressures in areas we would expect, particularly steel and construction products that are energy-intensive in their production processes or derived from oil. Reports that G7 countries will release oil and diesel reserves in the coming weeks could help ease some pressures on construction costs. However, the most direct effects are likely to be on haulage, plant operation and oil-derived products rather than a broad-based easing in costs overall.
‘Any relief will also be temporary as long as conflict-related disruption to energy supply persists, including strikes on Russian energy infrastructure. This makes cost management particularly challenging. When markets are volatile, assumptions made early in a project can become outdated more quickly and individual cost movements may diverge significantly from headline inflation.
‘For client-side cost consultants and quantity surveyors, it’s even more important to test early cost assumptions against the latest, relevant project data, using appropriate indices. The BCIS All-in Tender Price Index, for example, provides an updated estimate of tender price movement and can help inform adjustments as market conditions change.
‘For estimators, BCIS Schedule of Rates can provide a structured benchmark against which current pricing can be assessed. No single dataset removes market uncertainty, but using robust cost evidence alongside current project and supplier information can give all parties a stronger basis for negotiation, cost planning and risk management.’
DBT data show prices for fabricated structural steel recorded the greatest inflation in the 12 months to August 2026, up by 21.2%. This was followed by a 15.5% rise in prices for rigid pipes and fittings.
Prices for imported sawn or planed wood saw the steepest annual decrease of all resources measured with a 1.6% fall.
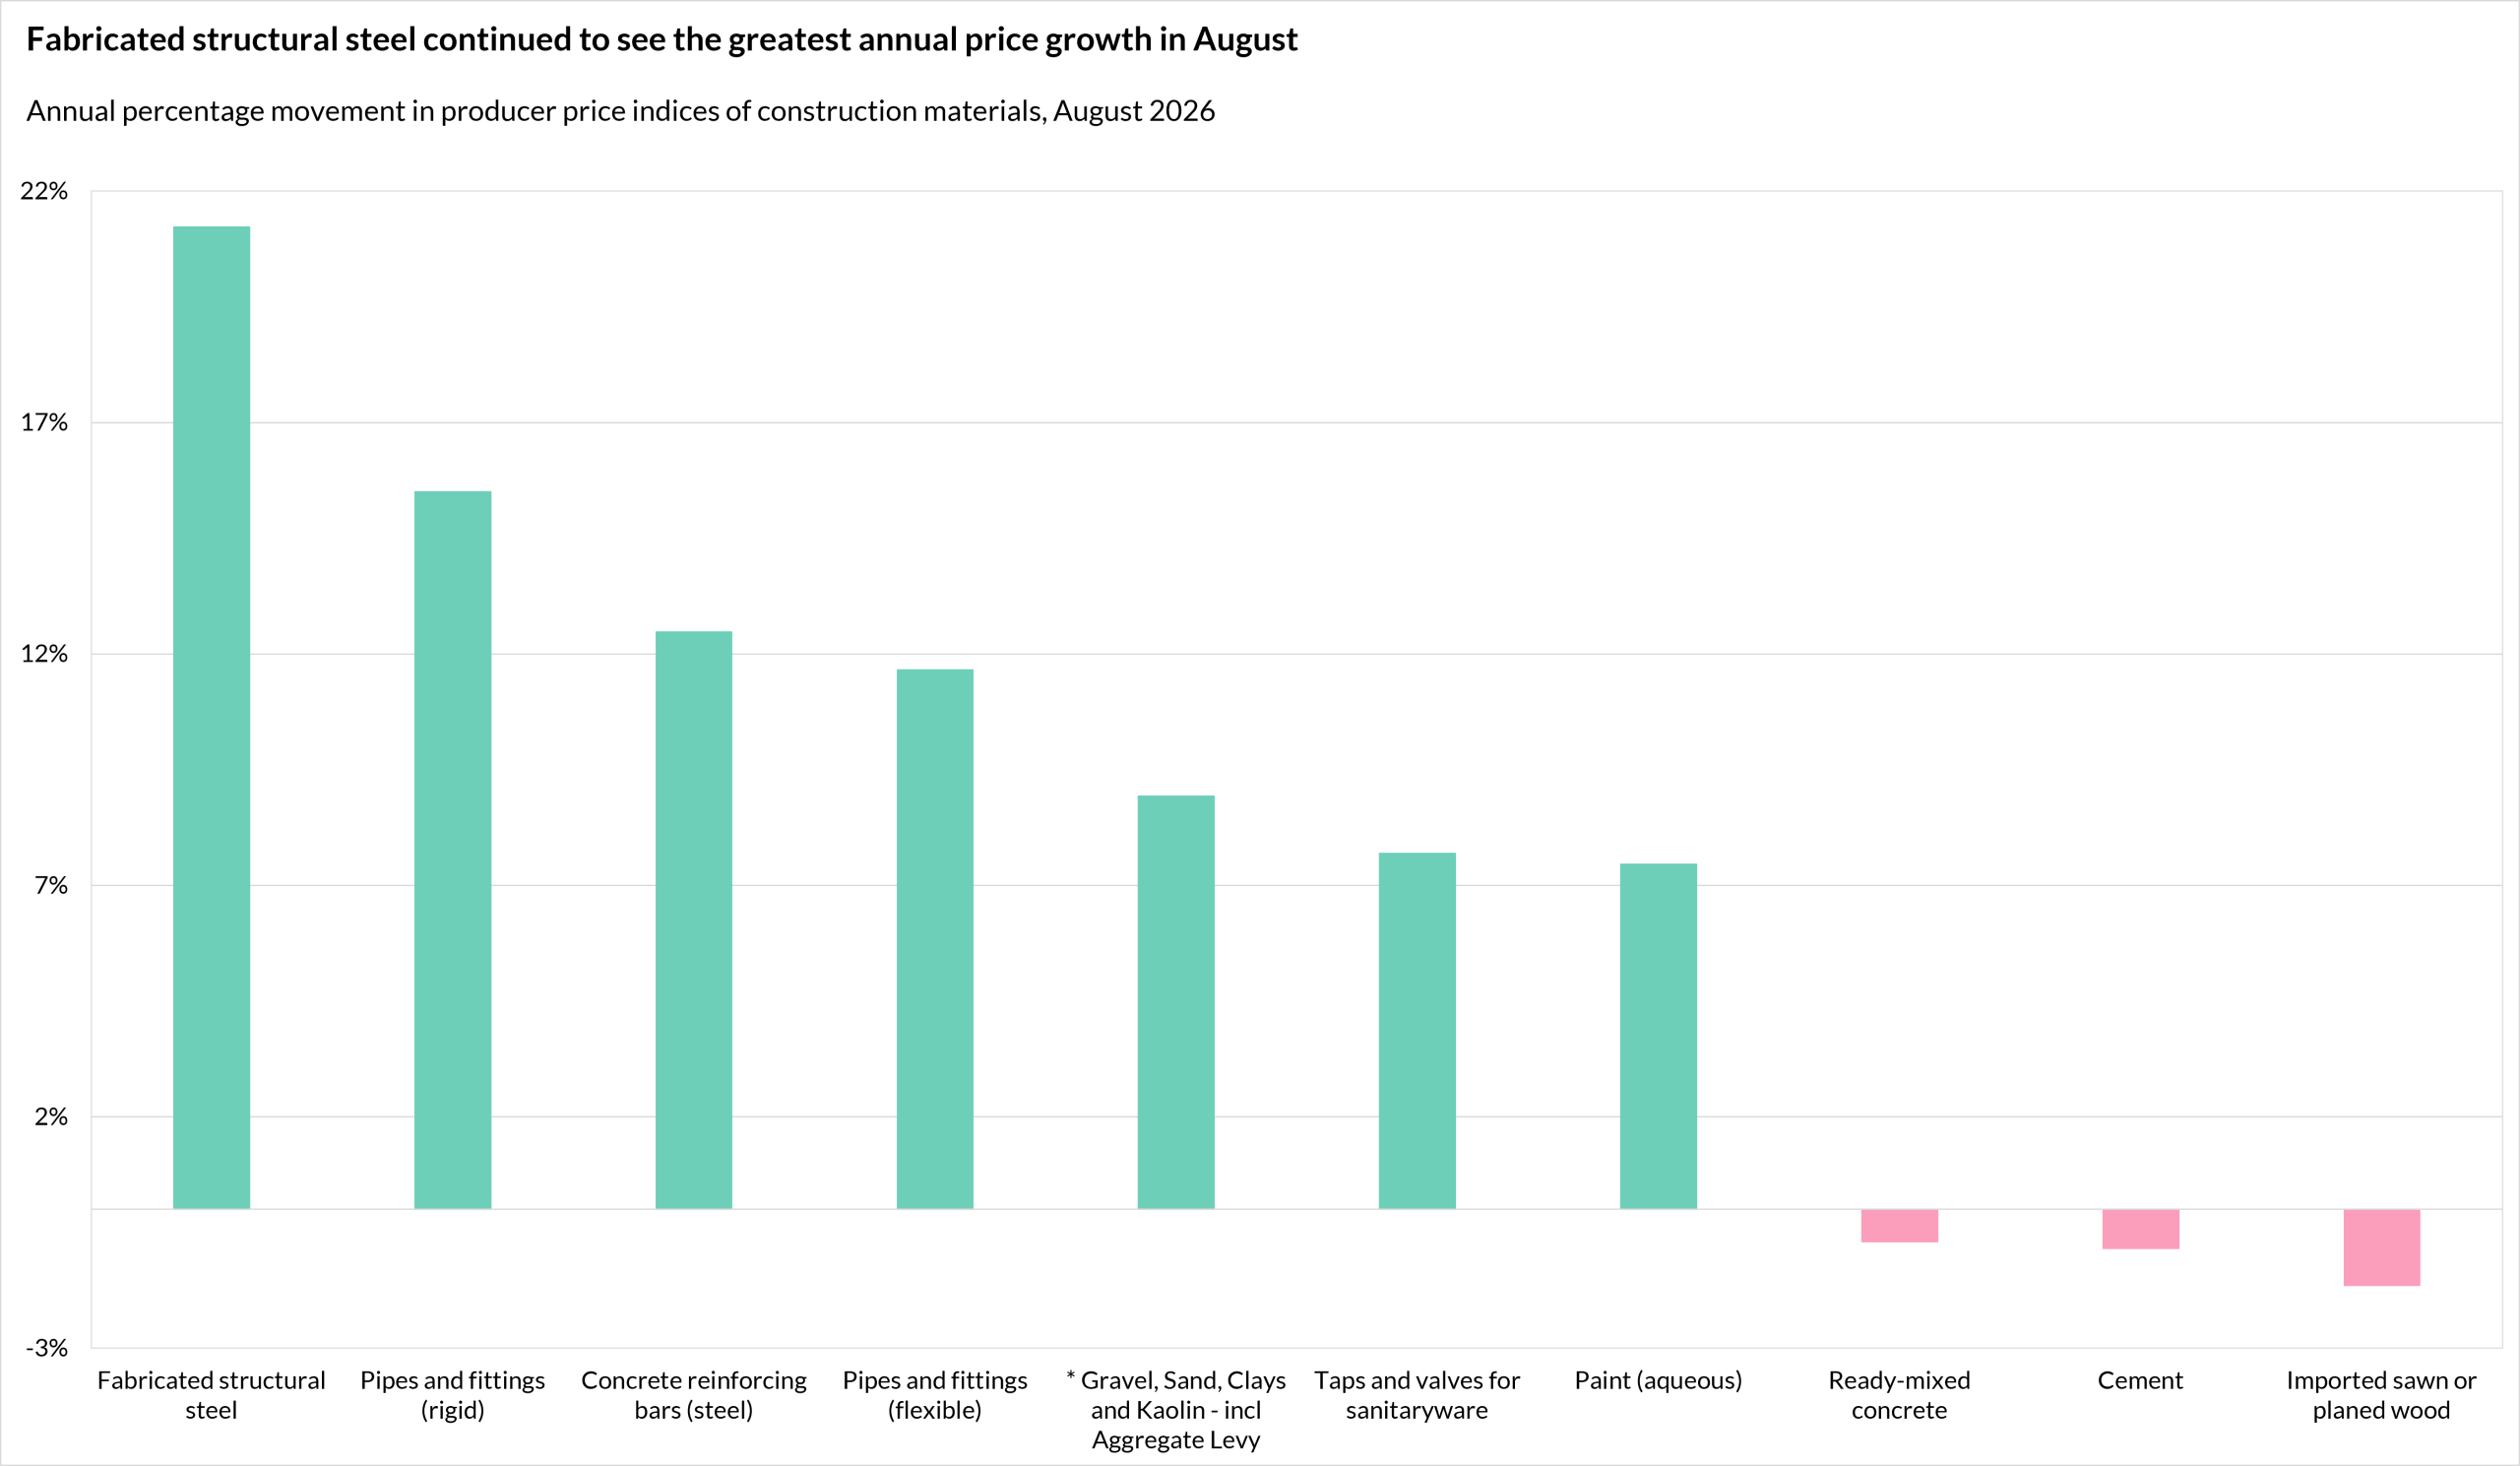
Source: Department for Business and Trade – Building materials and components statistics, Table 2. * DBT advises index values should not be relied upon for long-term contractual purposes, as they are based on relatively few quotes.
On a monthly basis, the greatest price increase was a 5.2% rise in prices for central heating boilers. The steepest decrease was a 2.7% fall in prices for bituminous mixtures based on natural and artificial stone.
The latest Builders Merchant Building Index (BMBI) report shows that builders merchants total volume sales in July 2026 were 7.6% lower than in July 2025.
Total value sales also decreased by 0.6% in this period, while prices were up by 7.6%.
The renewables and water saving category experienced the greatest fall in volume sales in the year to July 2025 with a 30.8% fall. This was followed by the heavy building materials and plumbing, heating and electrical categories with 11.1% and 10.7% decreases respectively.
To keep up to date with the latest industry news and insights from BCIS, register for our newsletter here.