The Building Cost Information Service (BCIS) is the leading provider of cost and carbon data to the UK built environment. Over 4,000 subscribing consultants, clients and contractors use BCIS products to control costs, manage budgets, mitigate risk and improve project performance.
Published: 02/10/2026
Geopolitical tensions are feeding into construction tender prices, but the effects remain uneven
When BCIS polled construction professionals in March 2026, less than a month after the US’s first air strikes on Iran, just over one-quarter (28%) said the conflict in the Middle East was already affecting UK construction tender prices. By September, that figure had risen to 57%, although it was slightly below July’s 59%.
The responses point to a market continuing to feel the effects of geopolitical disruption. However, the extent to which higher input costs are reaching tender prices depends on the materials, specialist packages and market conditions involved.
Across the polls, the proportion reporting an impact increased between March and July before easing slightly in September. Meanwhile, the share anticipating an impact within the next three months fell from 50% in March to 22% in September. A further 17% in September expected an impact within three to six months.
The September question received 218 responses. Attendees across the webinars were predominantly cost consultants and surveyors.
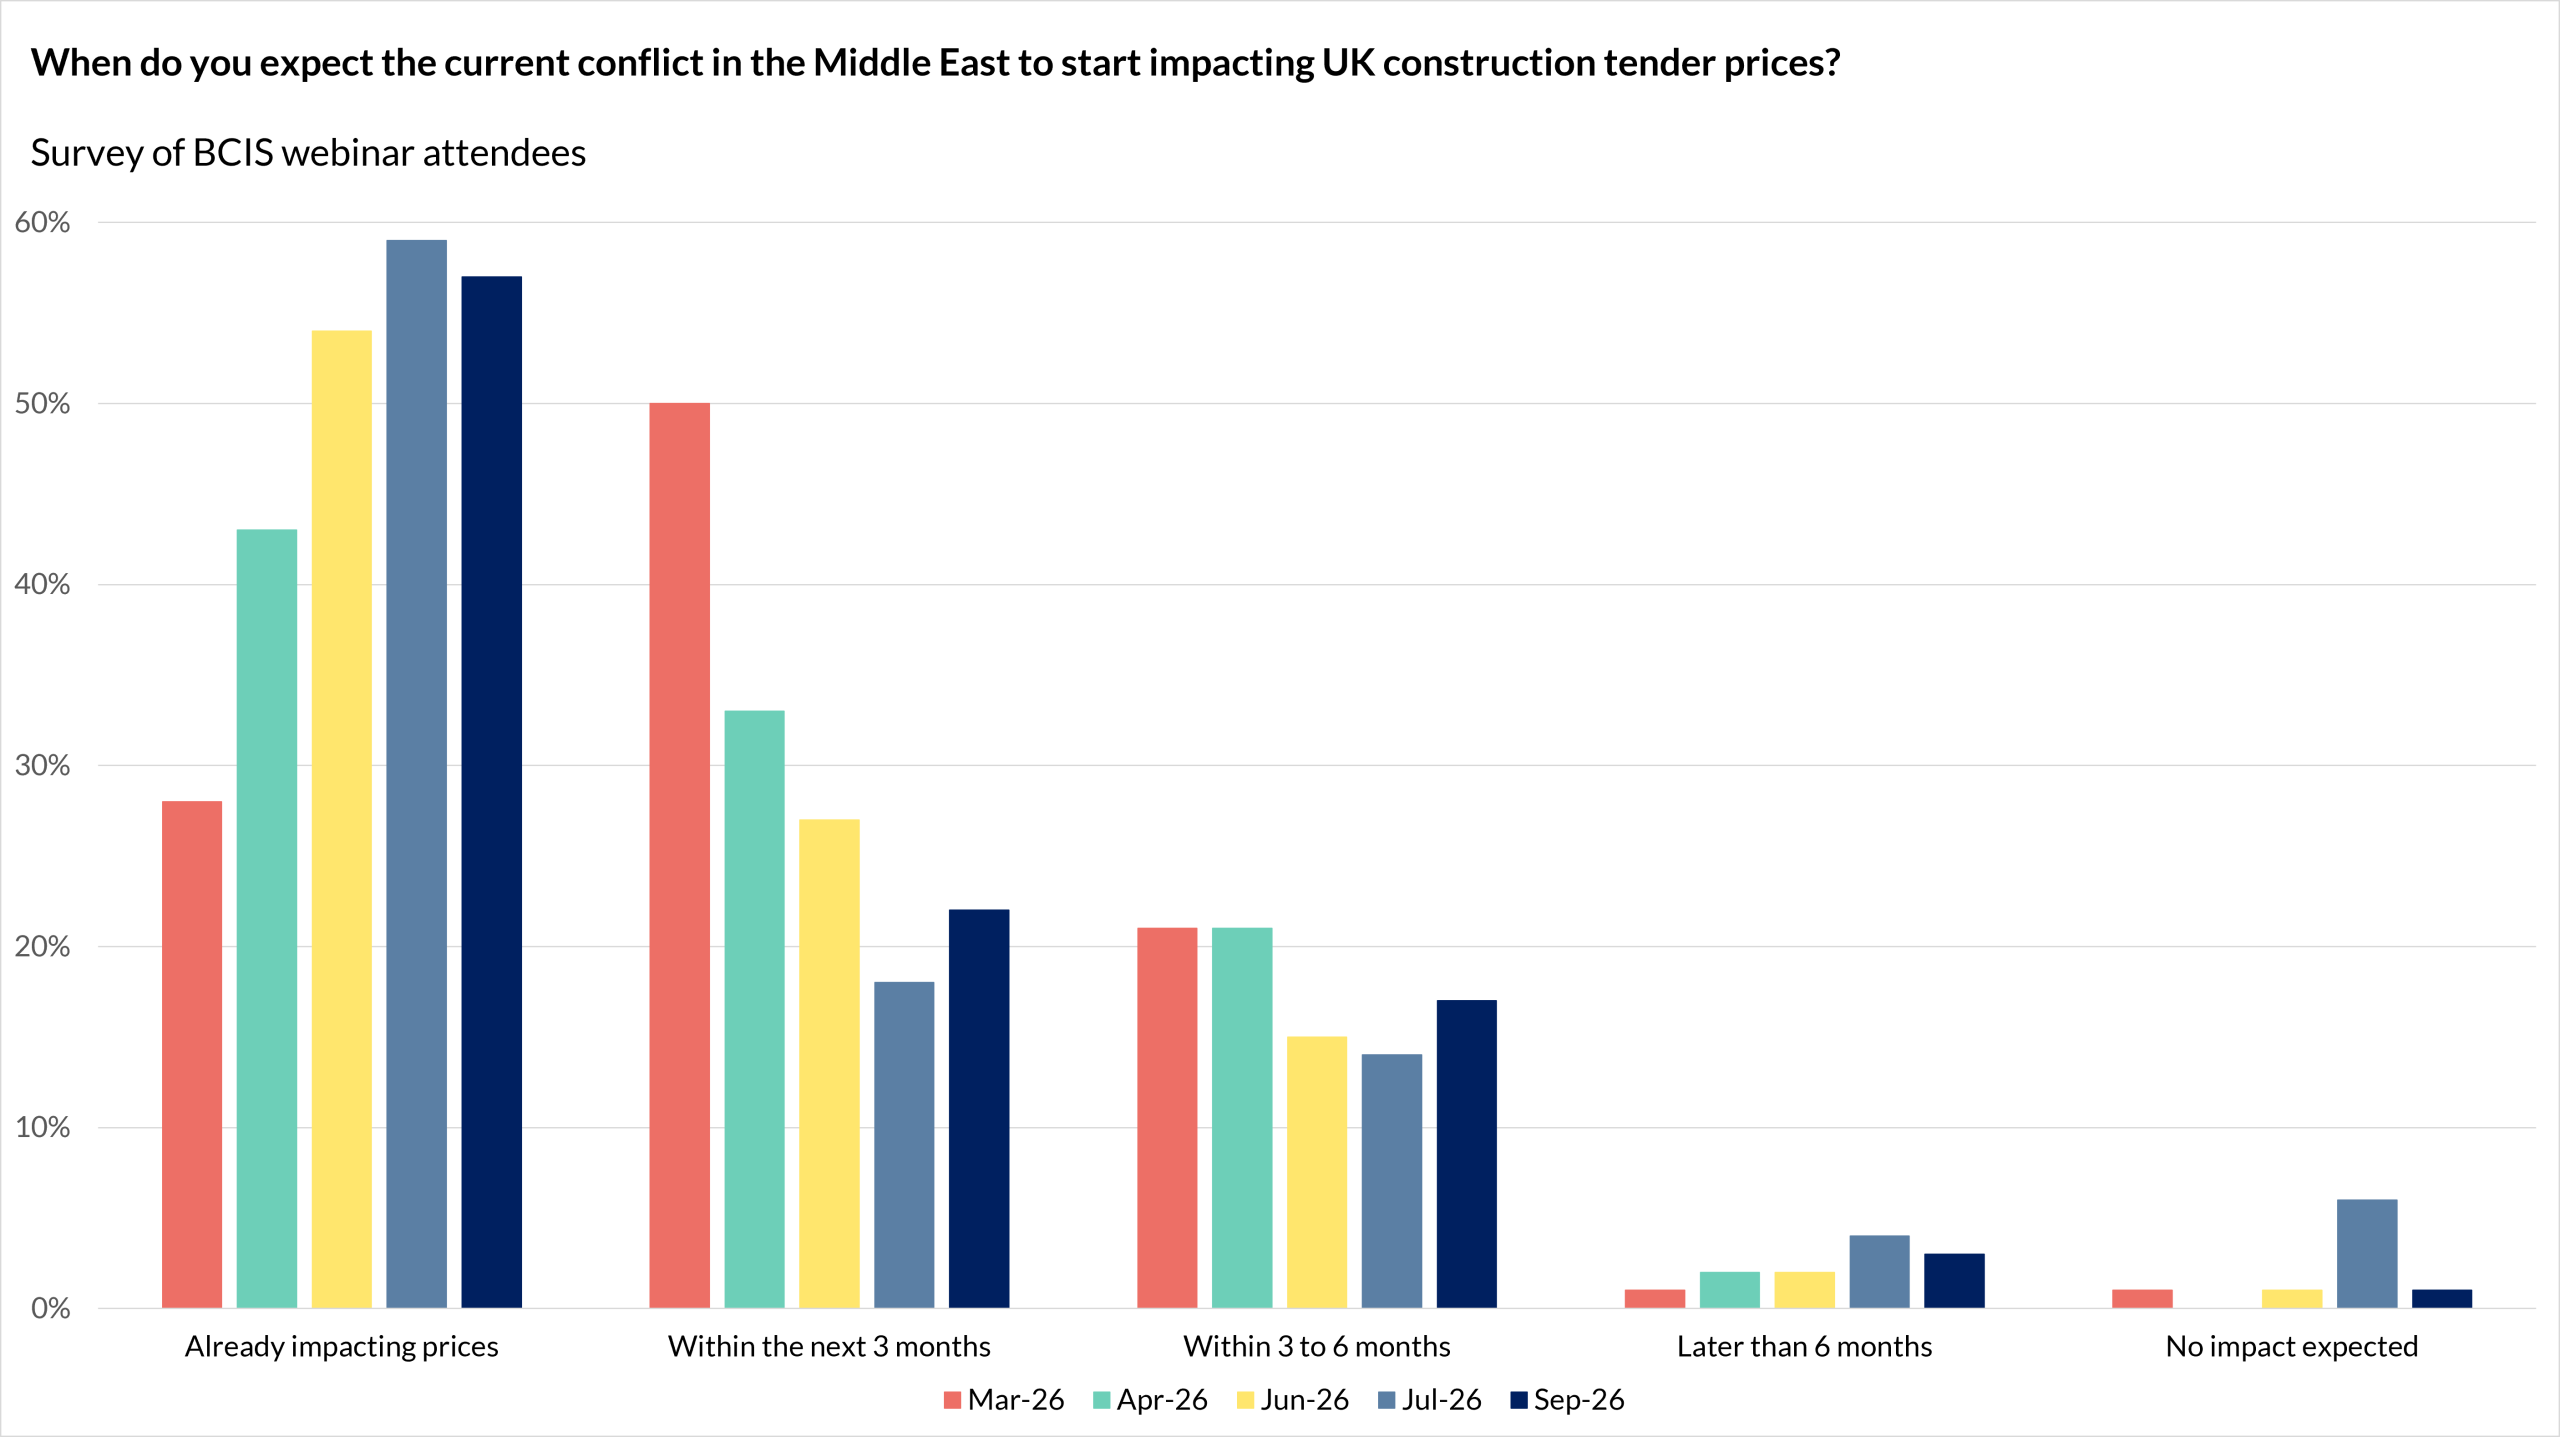
Source: BCIS surveys of webinar attendees, March to September 2026. Responses were anonymous, with sample sizes ranging from 218 to 396. The same question was asked at each webinar, but audiences varied; the results do not track the same group of respondents over time.
The latest BCIS TPI Panel commentary reinforces the uneven picture. In September, panellists reported mixed experiences of steel pricing, increases in oil-derived products and pressure on some specialist packages. The BCIS All-in Tender Price Index increased by an estimated 0.7% between 2Q2026 and 3Q2026, with annual growth of 3.2%.
Sam Parkin, senior economist at BCIS, said: ‘Fundamentally, price growth across the supply chain remains uneven. Some materials are seeing weaker growth amid subdued demand, while others are reacting quickly to Middle East developments. A lot of it depends on the material. For instance, an oil-derived product such as DERV sees fluctuations as oil prices change.
‘Equally, steel prices have been elevated because of the EU’s Carbon Border Adjustment Mechanism (CBAM) implemented in January 2026, alongside the increased domestic tariff and updated quotas.
‘How this transmits into tender prices varies, largely because tender pricing is more responsive to demand. With demand weakening across most output sectors, competitive pricing is likely to persist, potentially squeezing contractor margins further.
‘Although monthly insolvencies fell in August, they remain on course to stay elevated across 2026 as a whole. The combination of sustained cost pressures and weak demand presents a challenging outlook for contractors, particularly if output deteriorates further while oil and natural gas prices remain elevated. That said, an expected recovery in demand in mid- to late-2027 should give contractors greater scope to pass through some of the cost increases they have absorbed.’
Reconciling these findings requires looking at what is happening at different points in the supply chain. Higher energy, commodity and manufacturing costs do not necessarily translate immediately or uniformly into the prices contractors offer clients.
The latest ONS producer price data show that manufacturers’ input prices rose by 6.1% in the year to August 2026, while output prices rose by 3.7%, a difference of 2.4 percentage points. Annual input price inflation exceeded output price inflation in each of the six months from March to August. The August figures are provisional.
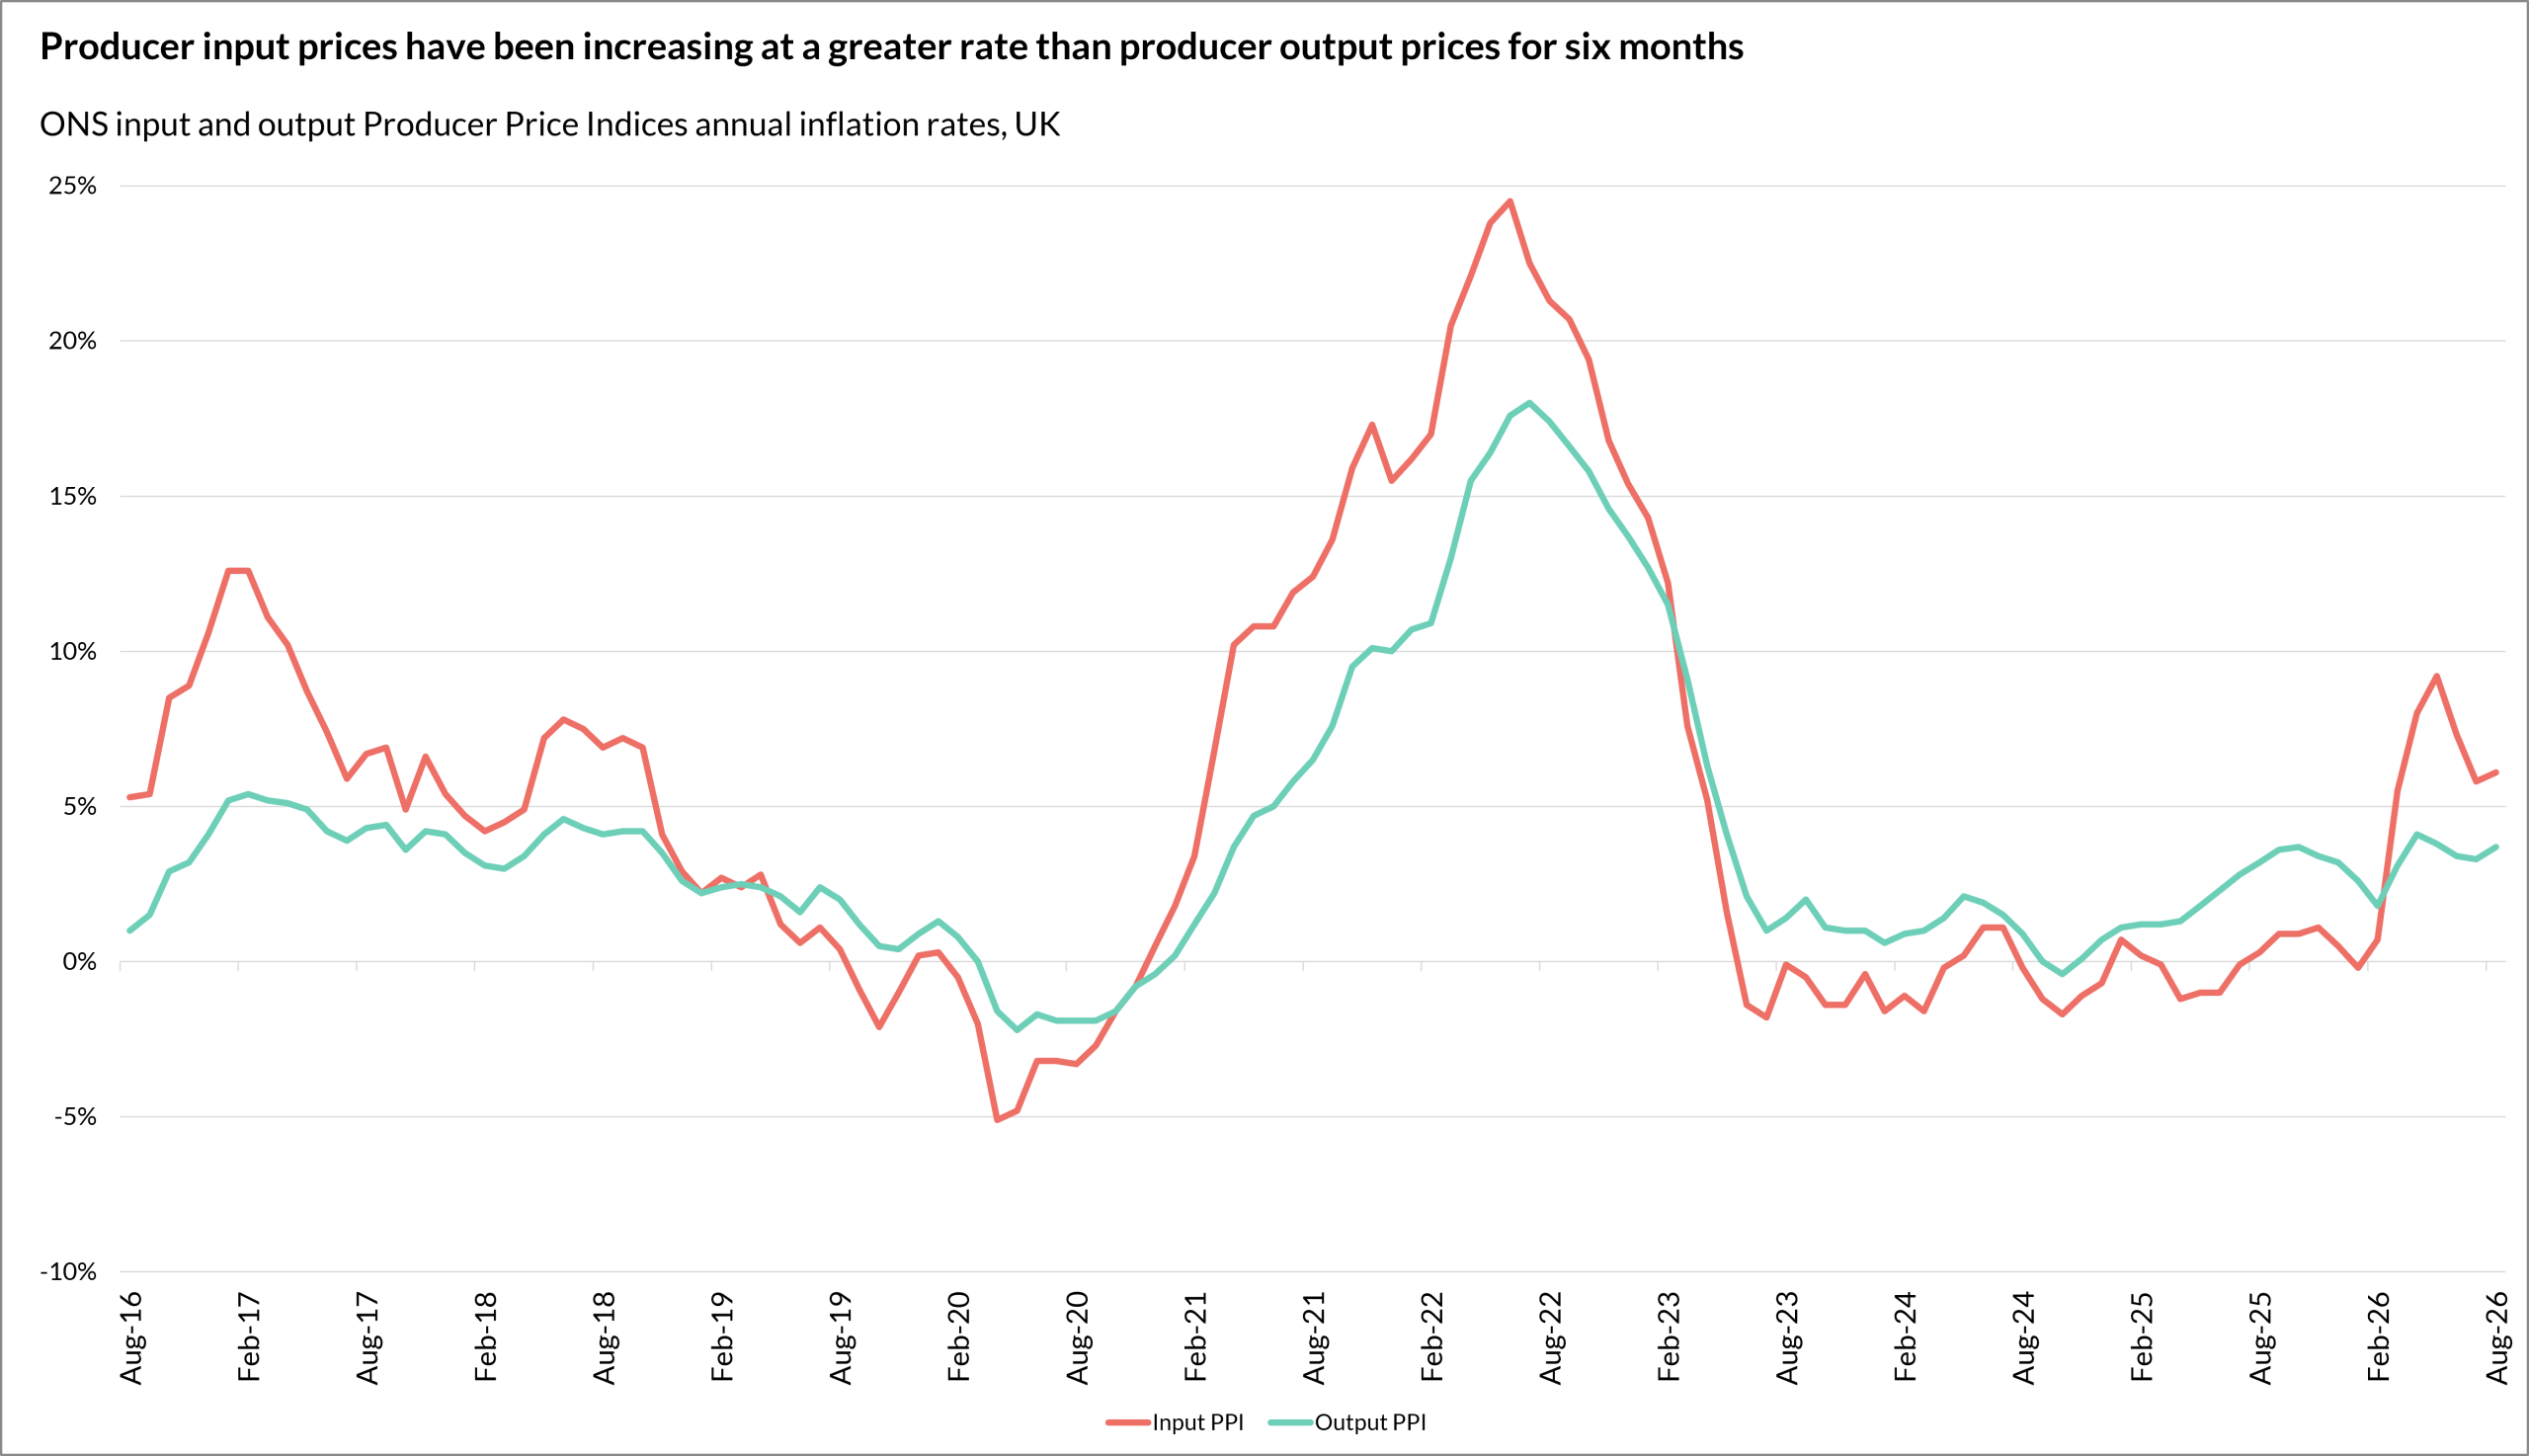
Source: ONS Producer Price Indices, August 2026 release.
‘This gap is likely to continue widening in the next release as oil prices have spiked once again,’ Parkin added. ‘Equally, natural gas prices are on the rise, and manufacturers will likely continue to absorb some cost pressure given the limited scope to pass higher prices on to consumers.
‘Nevertheless, manufacturers will look to recapture these absorbed costs once prices fall. From mid-2023 to early 2026, output prices were higher than input prices and that, in part, was due to this recapture. From a contractor perspective, I suspect higher costs passed on by manufacturers will likely remain a pressure point in the coming months. The difference, however, is that as demand recovers, contractors should have greater scope to pass some of these increased costs on to customers, rather than continuing to absorb them.’
The gap between input and output prices is consistent with pressure on manufacturers’ margins, but it does not directly measure margin absorption. The indices cover different baskets and weights, and output prices reflect costs beyond materials and fuel. They also cover manufacturing as a whole, rather than construction products alone.
Even so, the figures provide useful context for construction supply chains. Crude oil input prices rose by 26.7% annually in August. Factory gate prices for coke and refined petroleum products increased by 49.1%, while basic metals, fabricated metal products and machinery rose by 5.6%.
Timing is also a factor. Purchasing arrangements, existing stocks, supplier agreements and procurement programmes can influence when higher costs reach a project. Publication schedules can introduce a further delay between market movements and their appearance in reported data.
Producer input prices increased by 0.3% between July and August, following falls in June and July. Output prices rose by 0.7% in August. These movements show that input and selling prices can follow different paths even while both remain higher than a year earlier.
Weak demand continues to constrain cost pass-through. The S&P Global UK Construction Purchasing Managers’ Index registered 44.3 in August, its twentieth consecutive month below the 50 threshold separating expansion from contraction. Respondents reported subdued demand and fewer new projects.
The BCIS TPI Panel survey also identified stronger competition: 77% of respondents described contractors as eager to tender in 3Q2026, up from 67% in the previous quarter. However, appetite varied by region and project type.
That competitive pressure can limit the extent to which contractors pass higher costs on to clients. It also means apparently competitive tender prices need to be considered alongside the financial resilience and capacity of the supply chain.
The panel highlighted insolvencies, particularly among mechanical and electrical subcontractors, as a delivery risk. Demand from data centres and the New Hospital Programme is also competing for specialist capacity, adding pressure in parts of the market despite subdued activity elsewhere.
The pricing environment is therefore more differentiated than any single headline figure suggests. Competitive conditions may contain the overall tender price while individual packages face stronger increases.
Applying a uniform inflation assumption across a project is unlikely to capture that variation. Cost plans need to consider which elements are most exposed, when they will be procured and whether the prices returned are supported by a financially sustainable delivery plan.
‘Using headline figures, and particularly a broader inflation index like the Consumer Prices Index (CPI), is generally less appropriate for construction cost planning,’ Parkin said. ‘CPI often lags construction inflation and can therefore be misleading, as we have seen over the last six months, with CPI initially declining before rising slightly. At the same time, we have seen volatility across a range of construction materials, including steel, oil, chemicals and copper.
‘It is therefore important to consider cost assumptions on a case-by-case basis. If your project is particularly copper- or steel-heavy, for example, your costs could be rising more quickly than CPI currently suggests. Using BCIS’s Price Adjustment Formulae Indices provides a far more robust basis for budgeting by giving greater visibility of price movements across specific materials. Equally, they can highlight materials prices that are not currently rising, potentially presenting buying opportunities.’
BCIS subscribers can access the full tender price forecast, alongside the latest input cost indices and TPI panel commentary, via BCIS CapX.
To keep up to date with the latest industry news and insights from BCIS, register for our newsletter here.